FCA Names Seven Crypto Activities That Will Need UK Authorisation
The FCA's final perimeter guidance names seven crypto activities that will need UK authorisation from 2027, with applications open on 30 September 2026.

On this page
Key takeaways
- The FCA published final cryptoasset perimeter guidance on 16 September 2026 as policy statement PS26/18, naming seven activities that will require authorisation from 25 October 2027.
- The authorisation gateway opens on 30 September 2026, and the application window closes on 28 February 2027 for firms that want to rely on transitional cover.
- Existing Money Laundering Regulations registrations and other permissions will not convert automatically; firms must apply for authorisation, or a variation of permission if already authorised under FSMA.
- On 10 September 2026 the FCA, HMRC and the Metropolitan Police issued cease and desist letters at three London premises suspected of illegal peer-to-peer crypto trading.
- FCA authorisation does not compel banks to process crypto payments; nine of the ten largest UK retail banks still block or limit some crypto-linked transfers.
The Financial Conduct Authority published its final cryptoasset perimeter guidance on 16 September 2026, setting out the activities that will need authorisation once the UK's new regime takes effect on 25 October 2027. The policy statement, PS26/18, arrives two weeks before the authorisation gateway opens on 30 September 2026, and it is the clearest signal yet that Britain has finished with the light-touch approach that has governed crypto since 2020.
Related reading: Binance Pauses Withdrawals as Up to $5.6 Billion Leaves Its Wallets · World Opens a Stablecoin Super App in 150 Countries With Stripe on the Rails.
Until now, the FCA's direct oversight of crypto firms has been limited to anti-money laundering registration and financial promotion rules. The new framework folds crypto into the Financial Services and Markets Act 2000 (FSMA), the same statute that governs banks, brokers and asset managers. Firms that want to keep operating will need Part 4A authorisation, and the guidance explains how the regulator reads the perimeter Parliament set in the Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026.
"We are building a crypto regime that firms, consumers and international partners can trust," David Geale, the FCA's executive director of consumers, payments and competition, said in the press release. He added that the guidance "gives firms the clarity they've asked for so they can prepare with confidence."
The seven activities inside the perimeter
The guidance, published as a new chapter of the FCA Handbook's Perimeter Guidance Manual (PERG 18), confirms the list of regulated cryptoasset activities:
- Issuing qualifying stablecoins in the UK.
- Safeguarding, and arranging safeguarding of, qualifying cryptoassets and relevant specified investment cryptoassets.
- Operating a qualifying cryptoasset trading platform (QCATP).
- Dealing in qualifying cryptoassets as principal.
- Dealing in qualifying cryptoassets as agent.
- Arranging deals in qualifying cryptoassets.
- Arranging qualifying cryptoasset staking.
The list runs wider than the registration regime it replaces, which covered only exchange and custody services. It also reaches further than the EU's Markets in Crypto-Assets Regulation (MiCA) in one respect: the UK makes arranging staking a regulated activity in its own right, something MiCA does not regulate directly.
Two definitional points matter. A "qualifying cryptoasset" must be fungible, transferable and not solely a record of value or of contractual rights. The FCA also said products using hybrid stabilisation mechanisms, part backed by assets and part algorithmic, do not qualify as qualifying stablecoins, and that a wrapped stablecoin is not automatically a qualifying stablecoin, as Katten's analysis of PS26/18 notes.
The guidance applies a narrower "by way of business" test than the one used for regulated activities generally, so a person is caught only where they carry on the business of the activity in their own right rather than doing it incidentally. On territory, the FCA repeated that services supplied to UK consumers from overseas can count as carried on in the UK, and it confirmed there is no Overseas Persons Exclusion for the new activities. That puts offshore platforms serving UK retail customers squarely in scope.
The application calendar
The dates are fixed, and the runway is short relative to the size of the task:
- 30 September 2026: the authorisation gateway opens and the application period starts.
- 28 February 2027: the window closes for firms that want to rely on transitional arrangements.
- 25 October 2027: the regime comes into force.
Firms that file inside the window can keep operating under the savings provisions while the FCA assesses their applications. Firms that miss the February deadline cannot, and the guidance warns they may face restrictions on taking on new customers until they are authorised. The FCA says it aims to determine applications submitted in the window before the regime begins.
The core rulebook was already settled. On 30 June 2026 the FCA published five policy statements, PS26/9 to PS26/13, covering admissions and disclosures and market abuse, stablecoin issuance, regulated activities, prudential rules and the application of the Handbook. PS26/18 adds the perimeter guidance on top of that package after an April 2026 consultation, CP26/13, drew 78 responses.
Registrations do not carry over
The point the FCA has stressed hardest is that the old register does not roll into the new one. "Existing registrations and permissions won't convert automatically," the regulator said, and its policy statement spells out the consequences. Firms registered under the Money Laundering Regulations, authorised under the Payment Services Regulations or the Electronic Money Regulations, or already authorised under FSMA, all need to check whether they carry on a newly regulated activity. If they do, and no exclusion or exemption applies, they must apply for authorisation or, for existing FSMA firms, a variation of permission.
That is a change in kind, not degree. MLR registration asks a firm to demonstrate anti-money-laundering controls. FSMA authorisation brings the full apparatus: senior managers and certification, prudential capital, conduct rules including the Consumer Duty, safeguarding under a new CASS chapter, operational resilience and regular reporting. One compliance consultancy summarised the shift as moving from a narrow AML registration limited to exchange and custody to full Part 4A authorisation across seven activities.
The guidance is also not the last word. Because the Government laid a statutory instrument amending the underlying Cryptoasset Regulations, the FCA said it will consult again in October 2026 on targeted updates covering UK qualifying stablecoins, proprietary trading and market making, certain technology providers, decentralised protocols, safeguarding involving central securities depositaries and financial promotions. Final amended guidance is expected in early 2027.
Enforcement is already running
The perimeter guidance was not the only crypto news the FCA made that week. On 17 September it announced that it had, with HM Revenue & Customs and the Metropolitan Police, targeted three London premises suspected of illegal peer-to-peer crypto trading. Cease and desist letters were issued at all three. The operation took place on 10 September under the 2017 money laundering regulations, and it followed an April sweep that covered eight London addresses, Reuters reported.
The FCA's enforcement chief, Steve Smart, put the message bluntly: "Anyone running an unregistered peer-to-peer crypto business should assume we are looking at them." The regulator says there are currently no registered peer-to-peer crypto businesses in the UK, which means every commercial operation of that kind sits outside the register by definition. The timing is pointed: the crackdown landed a day after the guidance that tells firms how to get regulated.
Banks remain a separate gate
Authorisation settles a firm's status with the FCA. It does not settle its access to the banking system. Several major UK retail banks still cap, delay or block transfers to crypto exchanges, and the new framework regulates the crypto firms rather than the banks that serve their customers.
The Banker has reported that nine of the ten largest UK retail banks restrict some crypto-linked transactions, and the UK Cryptoasset Business Council has found that around 40% of bank-to-exchange transfers are blocked or delayed. The limits are specific. Barclays and HSBC UK cap transfers at GBP 2,500 per transaction and GBP 10,000 over a rolling 30 days, NatWest at GBP 1,000 per day and GBP 5,000 over 30 days, and Santander at GBP 1,000 per transaction and GBP 3,000 per 30 days, according to crypto.news. Chase UK blocks payments it identifies as crypto, while Metro Bank says it has not processed outbound crypto-exchange payments since November 2024.
HM Treasury has said it expects FCA-authorised crypto firms to be treated fairly and not to face restrictions simply because of their sector. But its March 2026 parliamentary answer described banking decisions as "largely commercial in nature," and there is no new rule compelling a bank to process a given payment. As Crowdfund Insider put it, authorisation does not by itself lift a customer's transfer limit or force a bank to move the money.
How the UK compares with the EU and the US
The UK's regime lands between two poles. The EU's MiCA has been fully applicable since December 2024, licensing cryptoasset service providers through national competent authorities with passporting across the European Economic Area. Britain is not adopting that model. It is embedding crypto activities in FSMA and the FCA Handbook, a design the FCA says lets it lean on the supervisory discretion and conduct standards it already applies to traditional finance. There is no passporting between the two regimes, so a firm serving both markets needs parallel authorisations, as comparative analyses note.
The substantive differences are real. MiCA defines a longer menu of services but leaves staking arrangement largely alone, while the UK makes arranging staking a named activity. On stablecoins, MiCA splits asset-referenced tokens from e-money tokens, whereas the UK separates qualifying stablecoins from electronic money and hands systemic sterling stablecoins to the Bank of England. Consumers in the UK also get the Consumer Duty, which several law firm comparisons describe as more demanding on conduct than MiCA's baseline.
The American picture is the mirror image. On 15 September 2026 the U.S. Senate failed to advance the CLARITY Act, the market-structure bill that would have divided oversight of digital assets between the SEC and the CFTC. Reuters reported that the bill fell short of the 60-vote threshold it needed, with four Republicans joining Democrats against it, and Congress headed for recess before the November midterms. That leaves U.S. crypto regulation to agency rulemaking, notably the SEC's proposed Regulation Crypto Assets, which a future commission could revise. The UK, by contrast, has legislation passed in February 2026 and a published rulebook with a fixed start date, even if its perimeter guidance is still being refined.
What to watch
Three things will show how smoothly the transition runs. The first is the October consultation, which will test how far the Government's statutory instrument narrows the perimeter for market makers, technology providers and decentralised protocols. The second is application volume once the gateway opens on 30 September; the FCA has not published how many firms it expects or how long it will take to decide their files, and the savings provisions reward filing early. The third is bank access, where a licence still does not guarantee a payment rail.
For now, the direction is set. After years in which crypto sat in a registration-and-promotions side lane, the UK has a defined perimeter, a named list of activities and a dated authorisation process. Firms have until 28 February 2027 to use it, and the clock starts on 30 September 2026.
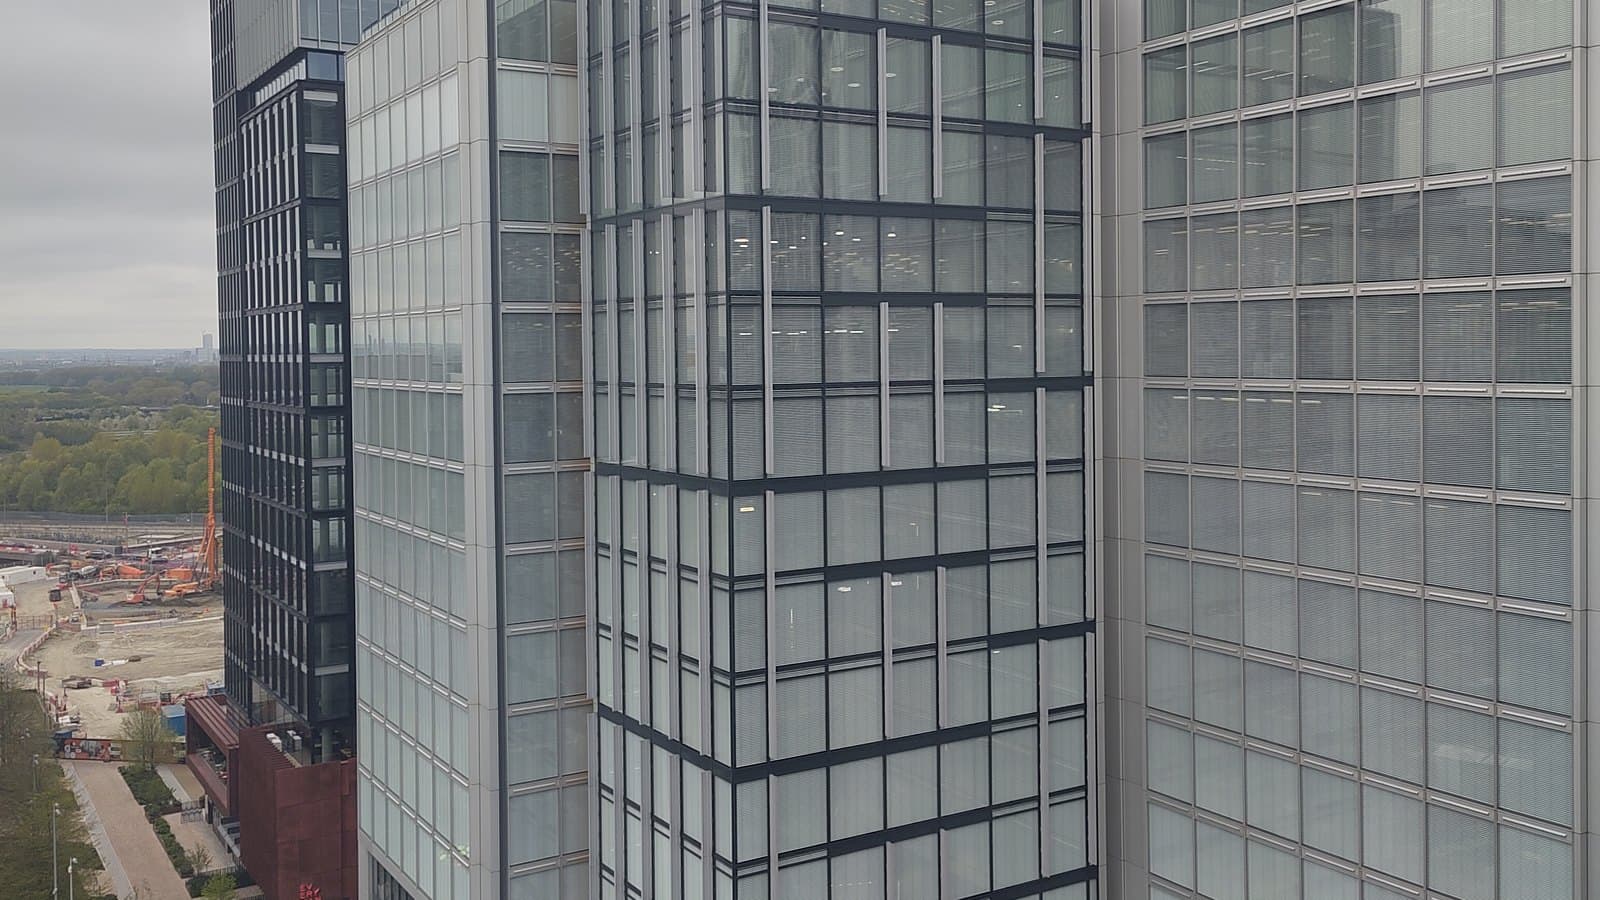
The 12 Endeavour Square offices in Stratford, London, home of the Financial Conduct Authority. Photo: Yirba / Wikimedia Commons (CC0).
Tags
Frequently asked questions
- Which crypto activities will need FCA authorisation from 2027?
- Seven: issuing qualifying stablecoins in the UK; safeguarding and arranging safeguarding of qualifying cryptoassets and relevant specified investment cryptoassets; operating a qualifying cryptoasset trading platform; dealing in qualifying cryptoassets as principal; dealing as agent; arranging deals; and arranging qualifying cryptoasset staking.
- Do existing FCA crypto registrations carry over to the new regime?
- No. The FCA says existing registrations and permissions will not convert automatically. Firms registered under the Money Laundering Regulations, authorised under the Payment Services or Electronic Money Regulations, or already FSMA-authorised must apply for authorisation or a variation of permission if they carry on a newly regulated activity.
- When can firms apply for FCA crypto authorisation?
- The gateway opens on 30 September 2026 and the application window closes on 28 February 2027 for firms wanting transitional cover. The full regime comes into force on 25 October 2027.
- Will FCA authorisation make UK banks process crypto payments?
- No. The new framework regulates crypto firms rather than banks. FCA authorisation of an exchange does not lift a customer's transfer limit or require a bank to process a payment, and banks keep their own fraud and risk policies.

TPW Editorial
Editorial Team
TechPastWeek's editorial team reports and edits every story we publish. We research each piece against primary and credible secondary sources, and a human editor reviews and signs off before it goes live.