Intel Can Fill Only About Half of CPU Demand as AI Inference Strains Its Fabs
Intel CEO Lip-Bu Tan says the chipmaker fills only about half of CPU demand as AI inference strains its fabs, and the 14A production timeline is in dispute.

On this page
Key takeaways
- Intel CEO Lip-Bu Tan said at Splunk's .conf26 in Denver in the week of September 14, 2026 that Intel can supply only about 50% of the CPUs its customers are asking for.
- Intel's second-quarter 2026 revenue was $16.1 billion, up 25% year over year, and its Data Center and AI segment grew 59% year over year to $6.3 billion.
- Intel's non-GAAP gross margin reached 41.8% in Q2 2026, up from 29.7% a year earlier, as fuller factories absorbed fixed costs.
- Intel's 18A process, used in Panther Lake laptop and Xeon 6+ server chips, is in high-volume production; Intel guided 14A for risk production in the second half of 2027 and a high-volume ramp in 2028.
- Intel raised its 2026 capital spending outlook to more than $20 billion and said 2027 capital spending will be significantly higher, mostly in the United States.
Intel chief executive Lip-Bu Tan used an appearance at Splunk's .conf26 conference in Denver in the week of September 14 to deliver an unusual admission: the chipmaker can fill only about half of the orders it is receiving. "CPU demand is so high that we can only supply 50% of customers," Tan said during a conversation with Cisco president Jeetu Patel, as reported by CTech. He added that other chief executives had been calling him to apologize for shortages of their own. "Many CEOs are calling me apologizing for not being able to produce enough," he said.
Related reading: Intel's Data Center Revenue Rose 78% and the Stock Fell 28.58% · Eight Tech Companies Are Evaluating Intel's 14A Node, and None Has Signed.
That 50% figure describes Intel's own supply against demand for its products, not the total processor market. Even so, the admission is a sharp turn for a company that spent much of the past decade being late with manufacturing, and it frames the central tension in Intel's turnaround: after years of struggling to sell what it could make, it now cannot make enough of what it can sell.
Fifty percent of demand, and an apology
Tan's explanation for the gap is a demand shift that Intel has been arguing for more than a year. The first phase of the AI boom ran on graphics processors used to train large models. The second phase, inference and agent-based software, leans on general-purpose CPUs, and Tan has built his public case for Intel around that idea.
"There are numerous agents, and in the future millions or trillions of agents will require resources," Tan said at the Denver event, according to CTech. "Sufficient computing power and security are needed to respond to this." The Motley Fool, which reported on the same appearance, described the driver Tan cited as an explosion in demand for CPUs to run AI inference, the work models and agents do after they are trained.
Intel has been making a version of this argument since at least the first quarter of 2026, when it said customers were deploying server CPUs alongside accelerators in ratios that were moving back toward the CPU. The result shows up in the company's reported numbers. Intel's Data Center and AI segment, which houses its Xeon server processors, is now growing far faster than the rest of the business.
"CPU demand is so high that we can only supply 50% of customers." — Lip-Bu Tan, Intel CEO, speaking at Splunk's .conf26 in Denver
A shortage of this scale is not confined to Intel. Tan has described an industry-wide squeeze across leading-edge logic wafers, memory and the substrates that sit under finished chips. Substrates, in particular, have become one of Intel's tightest constraints, and Tan said at .conf26 that Japanese and Taiwanese suppliers were locking up supply through prepayment.
The financial record behind the shortfall
The shortage is showing up most clearly in Intel's second quarter of 2026, reported on July 23. Revenue was $16.1 billion, up 25% year over year, which Intel called its strongest revenue growth in more than fifteen years. The Data Center and AI group brought in $6.3 billion, up 59% year over year and 24% from the prior quarter. The Client Computing and Physical AI Group, home to the PC chips, grew 13% to $8.9 billion. Intel Foundry reported $5.8 billion in revenue, up 31% year over year, with $293 million of that from external customers and an operating loss of $2.1 billion.
The margin line is where the shortage pays off. A semiconductor fab is a fixed-cost machine: whether it runs full or half-empty, the building and the tools cost roughly the same, so utilization drives profitability. Intel's non-GAAP gross margin climbed to 41.8% in the second quarter from 29.7% a year earlier, a gap of about 12 percentage points. Non-GAAP earnings per share came in at $0.42 against guidance of $0.20. Management guided third-quarter revenue to $15.8 billion to $16.8 billion, with a non-GAAP gross margin of 42% and non-GAAP EPS of $0.38.
What a shortage does to the numbers: when factories run close to full, each additional wafer spreads the same fixed costs over more output, which lifts gross margin. Intel's improvement from 29.7% to 41.8% in a year reflects both fuller utilization and better yields. The cost of a shortage is the mirror image: every order Intel cannot fill is revenue it never books, even if that demand is real and growing.
Tan has warned that the pressure runs beyond logic chips. At an AI Infrastructure Forum in Santa Clara on September 15, he said the memory shortage would get worse, pointing to high-bandwidth memory demand that suppliers have not been able to match, according to Sedaily. Intel has already factored memory costs into its PC outlook: on the second-quarter call, it said it expects PC consumption to be sub-seasonal in the second half of 2026 and down low double digits for the year, partly because of rising memory prices and constraints.
Why a shortage cuts both ways
Intel is spending to close the gap. The company raised its 2026 capital spending outlook to more than $20 billion, up significantly from what it expected entering the year, and said 2027 capital spending will be significantly higher again, with the vast majority going into its United States network. "AI-driven compute continues to strengthen, and to support expected growth this year and next across products and foundry, we are meaningfully increasing our investments in equipment, clean room space, and substrates," Tan said in Intel's second-quarter results release.
The risk is what customers do while they wait. A buyer who cannot get enough Xeon processors has two options: wait for more supply, or qualify a second source. In a market where rivals are eager for share, and where Intel's own next manufacturing node is still ramping, the waiting is not free. The Motley Fool made this point directly, noting that demand Intel cannot meet is revenue it does not collect and that customers who cannot get chips may not wait for 14A.
The second risk is time. A production start is not the same as volume. New process nodes ramp over several quarters, so even a 2027 start for 14A would not necessarily end the shortage that year. The Motley Fool argued the supply gap Tan described could persist well into 2027 for that reason.
For investors, the debate is less about whether the shortfall is real than about what is already priced in. Intel's stock has roughly tripled over the past year. CTech put the company's market capitalization at about $574 billion, with shares up roughly 175% since the start of 2026, though the stock closed at $108.60 on Friday, September 18, about 24% below its 52-week high of $142.35 reached on June 30. The Motley Fool noted that Intel trades at about 53 times next year's expected earnings, a multiple that assumes years of strong execution.
18A, 14A, and what happens next
The supply picture rests on two manufacturing nodes. The first, Intel 18A, is the most advanced process Intel manufactures in the United States and the basis for its newest products. It is in high-volume production behind Panther Lake, Intel's Core Ultra Series 3 laptop chips, and Xeon 6+, the Clearwater Forest server processor that is Intel's first server-class product on 18A. On the second-quarter call, Intel said 18A output came in about 25% above internal targets and was up more than 50% from the prior quarter.
Independent analysis suggests the node is maturing. GF Securities analyst Jeff Pu estimated Panther Lake yields on 18A at about 80%, and put Intel's 18A wafer capacity at roughly 40,000 wafers per month by the end of 2026, rising toward 60,000 per month by the end of 2027, as reported by TechPowerUp. Yield and capacity figures from outside analysts are estimates, not company disclosures, and Intel does not publish node-level yields.
The second node, 14A, is where the timelines diverge. Tan said at .conf26 that 14A begins production in the first quarter of 2027, according to The Motley Fool. Intel's own guidance, given with its July results, was more conservative: the company said 14A risk production for internal products is on track for the second half of 2027, with a decision already made to commit to high-volume ramps in 2028. In July, Intel described 14A defect density and transistor performance as outpacing 18A at a comparable stage, said its 0.5 process design kit was complete, and put the 0.9 kit on track for October.
The discrepancy matters because 14A is the node Intel hopes will win external foundry customers, and foundry economics depend on volume. Intel has said a chip design committed to 14A would need to be underway well before risk production begins. In September, Wccftech reported that Tan had moved 14A risk production up to the first quarter of 2027, while also reporting that Intel told the site that volume production on 14A will begin in the first quarter of 2028 and remains consistent with its second-quarter guidance. Those two statements describe different milestones, a development milestone and a manufacturing ramp, and only the company can reconcile them.
What to watch is straightforward. First, whether the demand Tan described holds through the second half of 2026, because Intel's July guidance implied growth cooling to about 19% at the midpoint from 25% in the second quarter. Second, whether 18A yields and capacity keep climbing enough to narrow the gap before 14A arrives. Third, whether customers who cannot get chips today stay loyal, or whether the shortage does lasting damage by pushing buyers toward a second source. A company that can sell only half of what customers want is in a better position than one that cannot sell what it builds. It is not, however, a comfortable one.
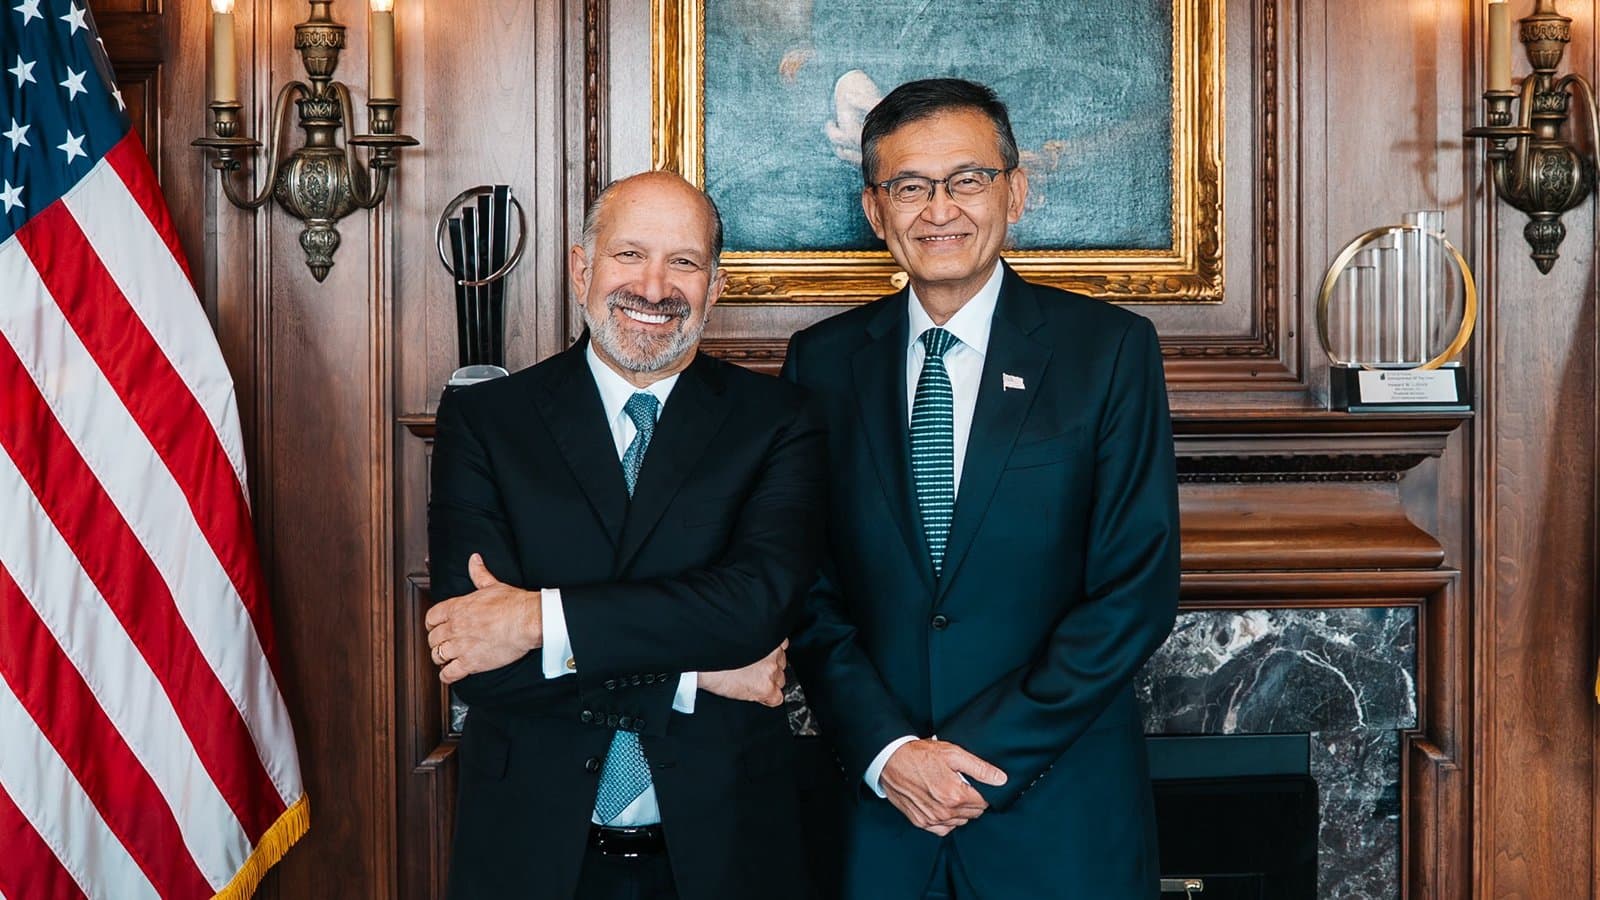
Cover: Intel CEO Lip-Bu Tan, right, with U.S. Commerce Secretary Howard Lutnick in Washington, August 22, 2025, by the United States Department of Commerce (public domain) via Wikimedia Commons, cropped 16:9.
Tags
Frequently asked questions
- How much of Intel's CPU demand can Intel currently meet?
- Intel CEO Lip-Bu Tan said in September 2026 that the company can supply only about 50% of what its customers are asking for. That figure describes Intel's own production shortfall against incoming orders, not its share of the total CPU market.
- Why is AI driving up demand for CPUs?
- Training large AI models runs mostly on GPUs, but inference and agentic workloads lean on general-purpose processors. Intel says it is seeing customers deploy server CPUs alongside accelerators in ratios that are moving back toward the CPU, and Tan has argued that millions of AI agents will each need compute and security resources.
- When will Intel's 14A process start production?
- The timing is contested. Tan said at Splunk's .conf26 that 14A begins production in the first quarter of 2027, according to The Motley Fool. Intel's July 2026 guidance put 14A risk production for internal products in the second half of 2027, with a high-volume ramp in 2028.
- Is Intel's supply shortage good or bad for the company?
- Both. Running factories full lifted Intel's non-GAAP gross margin by about 12 percentage points year over year. But demand Intel cannot fill is revenue it does not collect, and customers who cannot get chips may buy from rivals instead of waiting for Intel's next process.

TPW Editorial
Editorial Team
TechPastWeek's editorial team reports and edits every story we publish. We research each piece against primary and credible secondary sources, and a human editor reviews and signs off before it goes live.